
Having a life insurance policy can provide peace of mind and financial security for individuals and their loved ones. The primary purpose of life insurance is to offer a safety net in the event of unexpected death, ensuring that dependents are protected from financial hardship. There are two main types of life insurance: basic and supplemental, each serving distinct purposes.
Basic life insurance typically provides a minimum amount of coverage, often offered by employers as part of a benefits package. This type of insurance is usually low-cost or even free for employees, making it an attractive option for those who want to ensure their loved ones are protected without incurring significant expenses.
In contrast, supplemental life insurance offers additional coverage beyond what is provided by basic life insurance. This type of insurance is designed to provide extra financial protection for individuals who require more comprehensive coverage, such as those with dependents or significant financial obligations.
Must Read
For example, consider a scenario where an individual has a mortgage and dependent children. In this case, supplemental life insurance can help ensure that the mortgage is paid off and the children's educational expenses are covered in the event of the individual's passing.
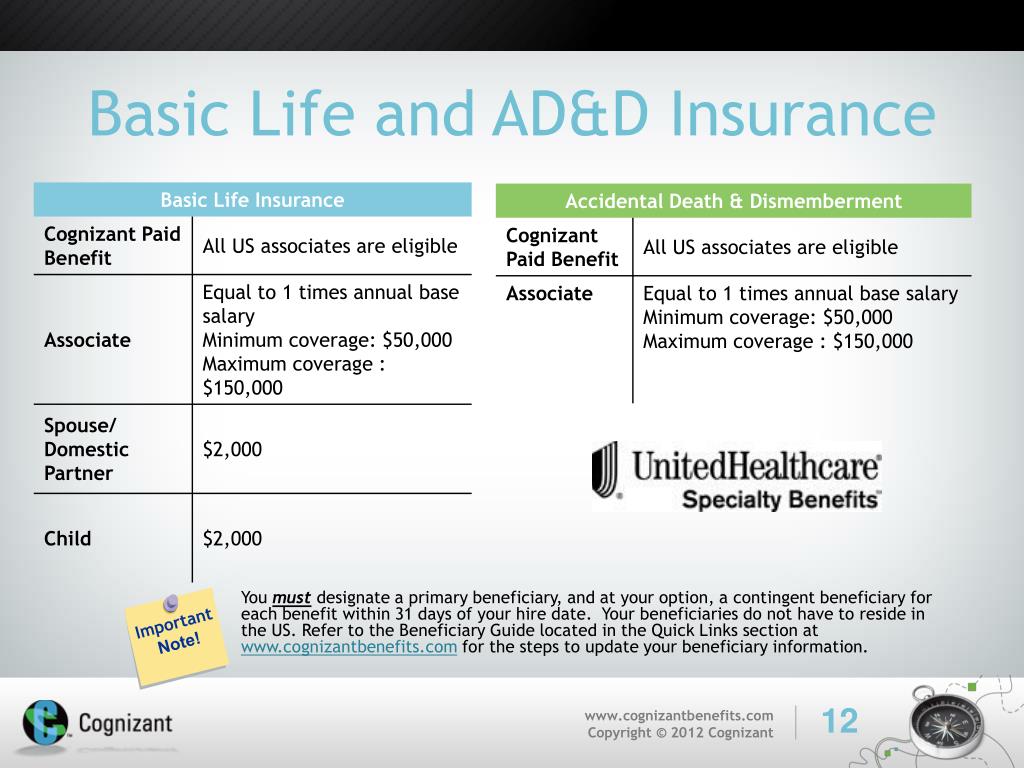 PPT - 2013 Benefits Orientation PowerPoint Presentation, free download
To explore life insurance options, individuals can start by reviewing their employer's benefits package or consulting with a licensed insurance professional. It's essential to assess personal needs and financial obligations to determine the appropriate level of coverage.
By understanding the differences between basic and supplemental life insurance, individuals can make informed decisions about their insurance needs and ensure that their loved ones are protected.
